First things first: what is an ITMO?
On September 24, 2026, Julie Dabrusin, Canada’s Minister of the Environment, Climate Change and Nature, announced that the federal government is developing a policy framework for companies to take part in international carbon markets. The plan involves a transferable form of climate progress: under Article 6.2 of the Paris Agreement, one country may transfer government-authorized emission reductions or removals to another country, where they count toward the recipient’s climate target. These are internationally transferred mitigation outcomes, or ITMOs.
Once a result is transferred, both countries must avoid counting the same reduction toward their own targets. They do this through a “corresponding adjustment,” supported by tracking and accounting systems that make ITMO trading possible.
Canada announces it is developing an ITMO framework
Dabrusin said the framework is intended to bring companies into international carbon markets, encourage investment in carbon removal technologies and nature-based solutions, and create export opportunities. Dabrusin described the goal as turning Canada’s natural advantages and homegrown climate innovation into investment, good jobs and new export opportunities.
The rules are still being developed. The government will consult provinces, territories, Indigenous organizations and other partners; the final rules will determine which projects qualify. Officials say the framework complements more than $13 billion in international climate finance included in the spring economic update. That funding made Canada one of the first countries to announce climate finance commitments beyond 2026.
The quality bar: real, additional, verified, permanent
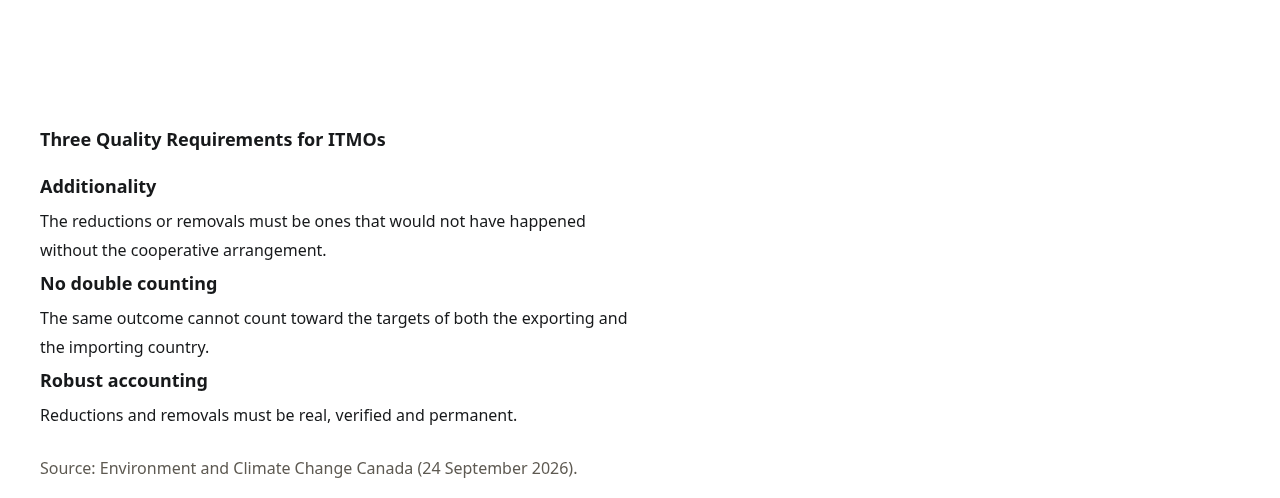
Canada says credits used as ITMOs must meet Article 6 requirements. Clear rules also help investors judge whether a claimed result can be trusted:
Additionality: the reduction or removal would not have happened without the cooperative arrangement.
No double counting: the exporting and importing countries cannot both count the same result toward their targets.
Robust accounting: reductions and removals must be real, verified and permanent.
Why Canada is betting on carbon removal
CarbonCredits.com, citing official data, reports that Canada emitted about 685 million tonnes of greenhouse gases in 2024, excluding land use. That was 10.3% below 2005. Oil and gas were the largest source, at 208 million tonnes. Reaching net zero requires cuts as well as removing carbon dioxide (CO₂) from the atmosphere or industrial processes and storing it securely.
Canada has geology suited to storage, clean power, and experience in energy and industry. Direct air capture (DAC) and bioenergy with carbon capture and storage (BECCS) could therefore grow into clean-technology export industries. If Canadian projects produce eligible, government-authorized mitigation outcomes, they could transfer them abroad under Article 6.2 agreements. The revenue could improve the economics of technologies that are costly in their early stages.
Citing Carbon Removal Canada modelling, CarbonCredits.com estimates that by 2050 carbon removal could add $78 billion a year to Canada’s GDP and create or support about 300,000 jobs.
UN NDC synthesis, October 2026: 94% keep the option of using Article 6
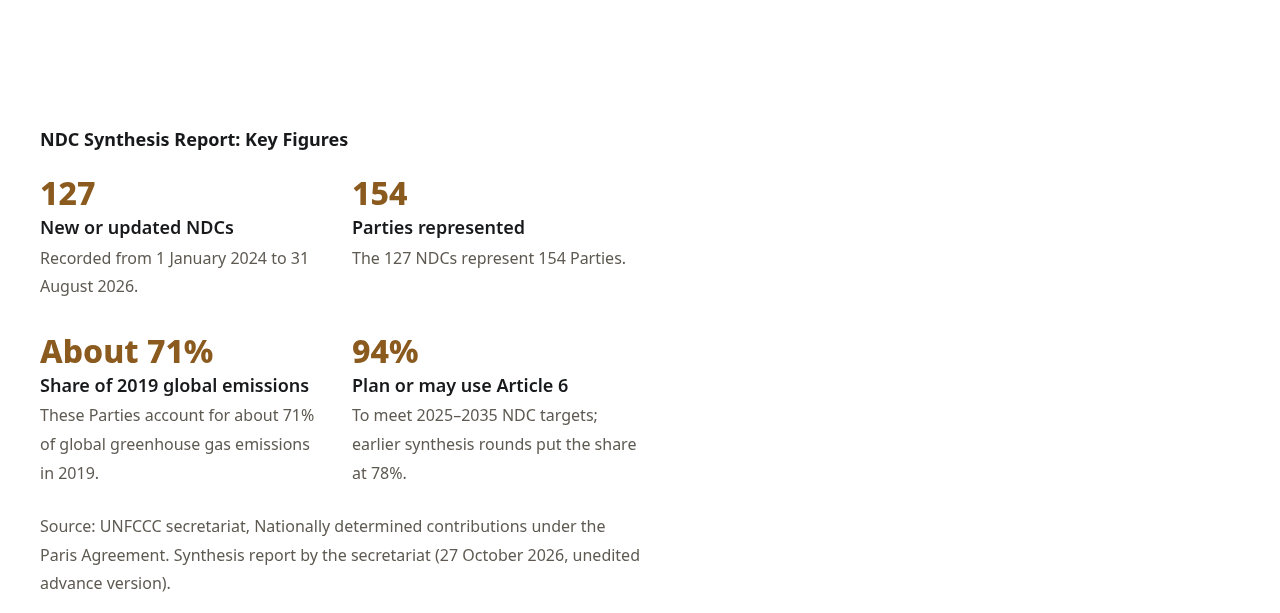
On 27 October 2026 the UNFCCC secretariat published Nationally determined contributions under the Paris Agreement. Synthesis report by the secretariat, an unedited advance version ahead of CMA 8. It covers 127 new or updated NDCs recorded from 1 January 2024 to 31 August 2026, representing 154 Parties and about 71% of global greenhouse gas emissions in 2019.
Of those Parties, 94% said they plan or may use the voluntary cooperation under Article 6 of the Paris Agreement to meet 2025–2035 NDC targets. Earlier synthesis rounds put the share at 78%. A Carbon Pulse introduction on 27 October likewise noted that the vast majority of countries kept the option of using Article 6 carbon markets to meet their targets.
The report groups cooperation intentions as follows: 81% of Parties explicitly mention using internationally transferred mitigation outcomes (ITMOs) under Article 6.2, or taking part in the Paris Agreement Crediting Mechanism (PACM) under Article 6.4; 21% express interest in non-market approaches under Article 6.8; and 13% refer only in general terms to international cooperation, without naming a mechanism. It also finds that submissions are moving from statements of intent to operational detail, including quantitative limits on transfers, eligible project types, environmental integrity standards, and domestic procedures for authorization and corresponding adjustments. The report notes that projected global emissions under current NDCs remain above a 1.5°C-consistent path, and that international transfers must avoid double counting and protect environmental integrity.
What it means for Taiwan (our view)
Our view: Taiwan is not a Party to the UNFCCC, so it would need other arrangements to connect with Article 6 authorizations and corresponding adjustments. Canada’s focus on additionality, permanence and avoiding double counting offers reference points for Taiwan’s system design.
The carbon fee is already being collected: the first carbon fee payments were due on June 1, 2026. All 461 facilities at 240 companies declared and paid, for a total of NT$4.97 billion.
Foreign credits can be used, up to a cap: under the Regulations Governing the Collection of Carbon Fees, businesses that are not at high risk of carbon leakage may use foreign emission-reduction credits recognized by the Ministry of Environment to offset chargeable emissions, up to 5%. The cap for domestic emission-reduction credits is 10%.
Questions remain for the rules: When the Ministry of Environment recognises foreign credits, Article 6 authorisation and corresponding-adjustment requirements, and how domestic credit quality and accounting rules align with international practice, remain points for Taiwan’s system design.
Sources (5)
Sources
Environment and Climate Change Canada, Federal Government developing framework for greater international cooperation on carbon markets (September 24, 2026): https://www.canada.ca/en/environment-climate-change/news/2026/09/federal-government-developing-framework-for-greater-international-cooperation-on-carbon-markets.html
CarbonCredits.com, How Canada’s New ITMO Framework Could Unlock International Carbon Markets (October 2, 2026): https://carboncredits.com/how-canadas-new-itmo-framework-could-unlock-international-carbon-markets/
Ministry of Environment press release (in Chinese), a key milestone for Taiwan’s carbon pricing system: carbon fees declared by companies total NT$4.97 billion (June 3, 2026): https://enews.moenv.gov.tw/moenv-news/zh-tw/News/1628
Ministry of Environment laws and regulations database (in Chinese), Regulations Governing the Collection of Carbon Fees: https://oaout.moenv.gov.tw/law/LawContent.aspx?id=GL007914
- UNFCCC secretariat, Nationally determined contributions under the Paris Agreement. Synthesis report by the secretariat, 27 October 2026: https://unfccc.int/documents/662352
Leave a comment
Comments are reviewed before publication. Email is private and used only when contact is necessary. Privacy notice